Economy & Markets
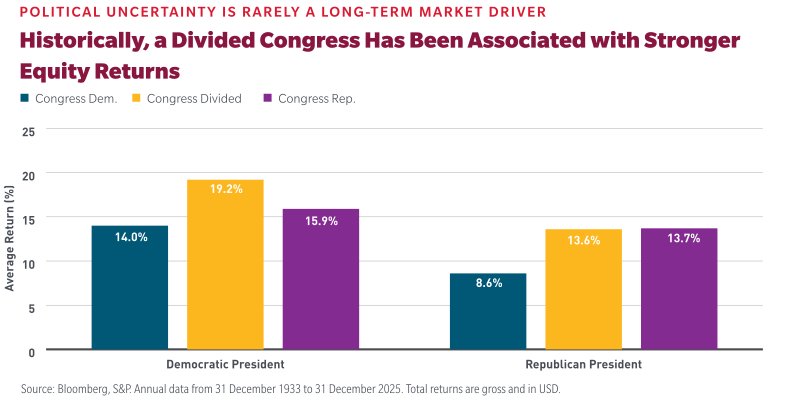
| Markets have historically looked past political volatility |
MFS PERSPECTIVE
|
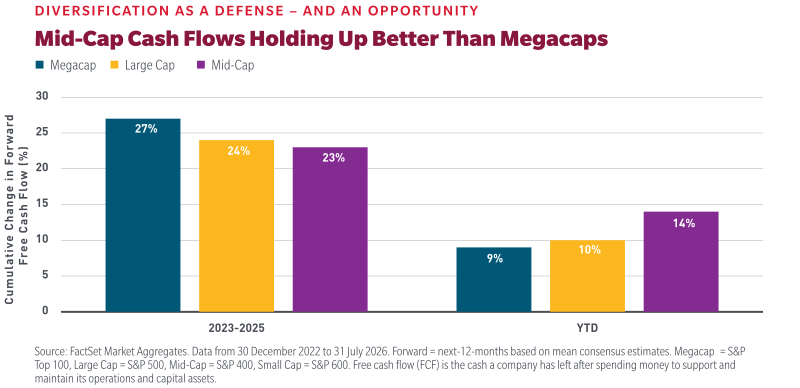
| Earnings growth expanding beyond megacaps |
MFS PERSPECTIVE
|
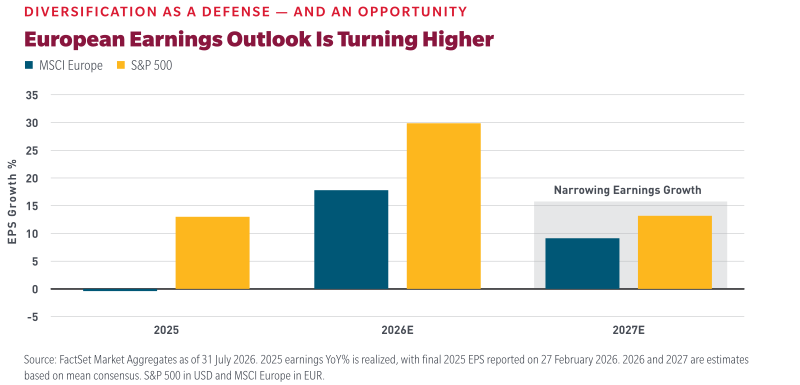
| Europe: More than a valuation story |
MFS PERSPECTIVE
|
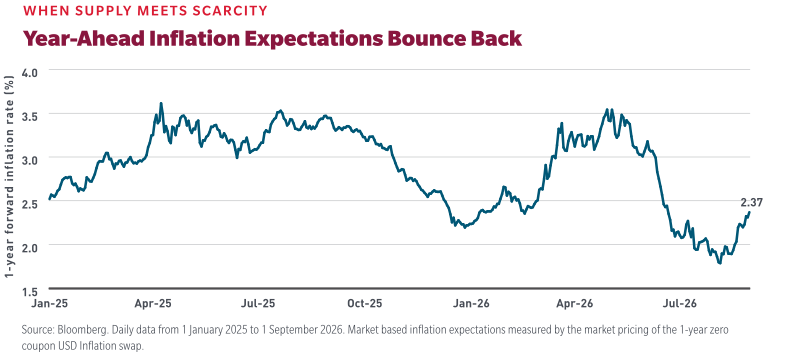
| Inflation expectations remain volatile |
MFS PERSPECTIVE
|
Equity
Assets Class Views
|
Fundamentals → |
Earnings Revisions ↑ |
Macro →
|
|
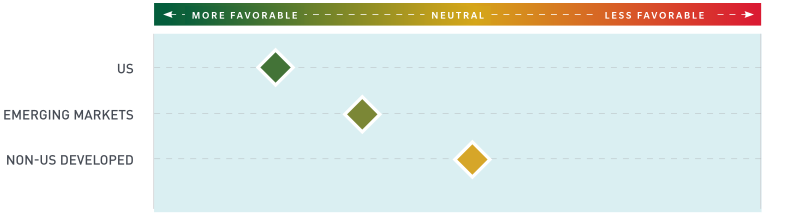
Emerging MarketsDespite chip stock volatility, EM fundamentals remain solid, and growth is improving, supporting a broad opportunity set from the AI supply chain to industrial metals. While China’s economy remains weak despite blockbuster IPOs, markets tied to manufacturing, infrastructure, and technology investment appear best positioned to benefit.
|
Non-US DevelopedEurope and Japan may offer a way to broaden client equity exposure beyond a US market increasingly defined by the AI trade. Valuations remain compelling, balance sheets are solid, and improving cash generation could support rerating potential.
|
US Equity
Assets Class Views
|
Fundamentals ↑ |
Earnings Revisions ↑ |
Macro →
|
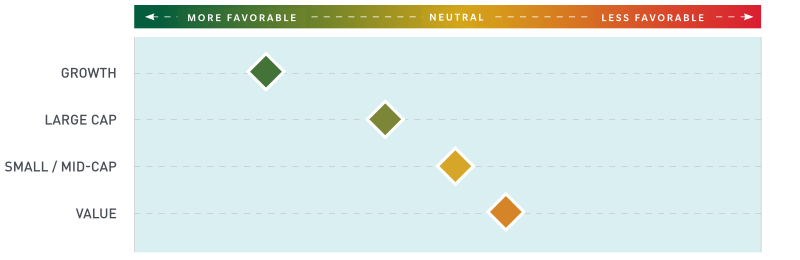
GrowthAI capex remains a key support for US growth equities, but the story is shifting beneath the surface. Headline indices may mask meaningful rotation as markets reassess the winners from AI investment and the companies best placed to benefit as AI moves into real-world implementation.
|
Large CapEven allowing for a recent boost from non-operating gains, US large-cap earnings remain robust. But leadership continues to rotate as the AI landscape evolves and markets reassess winners and identify companies best placed to benefit as AI shifts from an infrastructure buildout to real world adoption.
|
Small/Mid-CapThe SMID-cap outlook remains constructive. This year’s gains have been driven by rising earnings expectations rather than higher valuations, which leaves the rally on firmer footing. Valuations remain undemanding, and further upside is likely if rates ease and earnings strength broadens beyond health care and energy.
|
ValueValue remains the anti-AI trade and offers some of the cleanest diversification from tech-heavy indices. A large tech underweight is a near-term headwind, but health care’s earnings outlook is improving as pipelines mature, cost pressures ease, and policy risks fade, with energy and financials offering reasonably valued earnings growth.
|
Fixed Income
Assets Class Views
|
Fundamentals ↑ |
Technicals → |
Valuations ↓
|
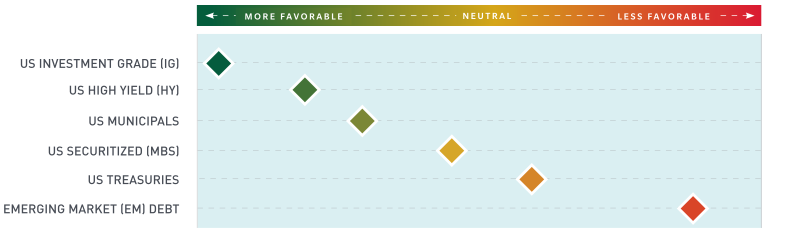
US Investment GradeCorporate fundamentals are robust, profit margins remain elevated, and free cash flow generation has been increasing. Despite geopolitical uncertainty, the business environment remains strong, as illustrated by remarkable S&P 500 earnings growth in Q2. Spreads remain tight, but their resilience helps position US IG well compared with purely rate driven asset classes. In addition, all-in yields are quite attractive by historical standards. |
US HYGeopolitical uncertainty hurt sentiment as growth fears pushed recent fund flows into negative territory. After early widening, spreads are now tighter than pre-war levels. With valuations rich and technicals weak, we prefer being up in quality.
|
US MunicipalsLike Treasuries, municipal valuations have become more attractive with tax exempt yields back above 3.6%. Fundamentals have benefited from strong growth in state tax receipts, and solid fund flows are helping absorb a wave of heavy issuance. |
US SecuritizedMortgage yields have risen, while spreads remain historically tight. Technicals were strong, supported by $200B in GSE buying of MBS amid limited issuance. Going forward, technicals may soften while valuations are rich.
|
US TreasuriesGeopolitical, fiscal, and monetary concerns have pushed market rates higher. But even with yields now more compelling, we remain neutral given the policy risks and macro uncertainty. Technicals are adequate as foreign demand remains healthy. |
EM DebtResilient fundamentals and attractive yields remain supportive. However, spreads are quite tight and may not fully compensate investors for higher uncertainty, leading us to stay selective and favor liquid sovereigns over corporates. |
Industry Flows
Money in motion by Morningstar category
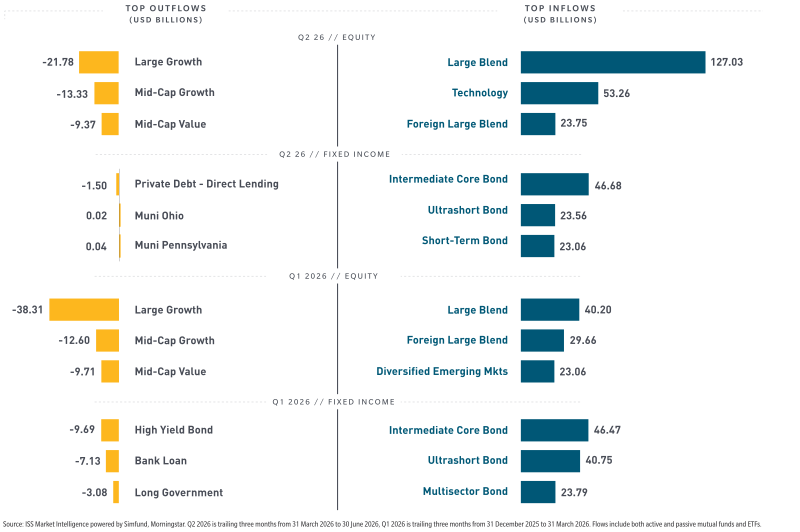
Source: 1FactSet Portfolio Analysis as of 31 July 2026.
The views expressed herein are those of the MFS Strategy and Insights Group within the MFS distribution unit and may differ from those of MFS portfolio managers and research analysts. These views are subject to change at any time and should not be construed as MFS’ investment advice, as portfolio positioning, as securities recommendations, or as an indication of trading intent on behalf of MFS. No forecasts can be guaranteed. The Market Pulse leverages the firm’s intellectual capital to provide perspective on broad market dynamics that are top of mind for asset allocators. We celebrate the rich diversity of opinion within our investment team and are proud to have talented investors who may implement portfolio positions and express different or nuanced views to those contained here, which are aligned to their specific investment philosophy, risk budget and entrusted duty to allocate our client’s capital responsibly.
Approach and methodology: The Market Pulse provides an outlook over a 12-month investment horizon for major asset classes as well as considerations of the prevailing market conditions. Views are driven by both quantitative and qualitative inputs, including, but not limited to, macroeconomic data, valuations, fundamentals and technical variables. The views expressed herein are those of the MFS Strategy and Insights Group within the MFS distribution unit and may differ from those of MFS portfolio managers and research analysts. These views are subject to change at any time and should not be construed as MFS’ investment advice, as securities recommendations, as portfolio positioning, or as an indication of trading intent on behalf of MFS. No forecasts can be guaranteed.
Index data source: MSCI. MSCI makes no express or implied warranties or representations and shall have no liability whatsoever with respect to any MSCI data contained herein. The MSCI data may not be further redistributed or used as a basis for other indices or any securities or financial products. This report is not approved, reviewed or produced by MSCI.
Frank Russell Company ("Russell") is the source and owner of the Russell Index data contained or reflected in this material and all trademarks, service marks and copyrights related to the Russell Indexes. Russell® is a trademark of Frank Russell Company. Neither Russell nor its licensors accept any liability for any errors or omissions in the Russell Indexes and/or Russell ratings or underlying data and no party may rely on any Russell Indexes and/or Russell ratings and/or underlying data contained in this communication. No further distribution of Russell Data is permitted without Russell's express written consent. Russell does not promote, sponsor or endorse the content of this communication.
“Standard & Poor’s® ” and S&P “S&P® ” are registered trademarks of Standard & Poor’s Financial Services LLC (“S&P”) and Dow Jones is a registered trademark of Dow Jones Trademark Holdings LLC (“Dow Jones”) and have been licensed for use by S&P Dow Jones Indices LLC and sublicensed for certain purposes by MFS. The S&P 500® is a product of S&P Dow Jones Indices LLC, and has been licensed for use by MFS. MFS’ Products are not sponsored, endorsed, sold or promoted by S&P Dow Jones Indices LLC, Dow Jones, S&P, or their respective affiliates, and neither S&P Dow Jones Indices LLC, Dow Jones, S&P, their respective affiliates make any representation regarding the advisability of investing in such products. BLOOMBERG® is a trademark and service mark of Bloomberg Finance L.P. and its affiliates (collectively “Bloomberg”). Bloomberg or Bloomberg’s licensors own all proprietary rights in the Bloomberg Indices. Bloomberg neither approves or endorses this material, or guarantees the accuracy or completeness of any information herein, or makes any warranty, express or implied, as to the results to be obtained therefrom and, to the maximum extent allowed by law, neither shall have any liability or responsibility for injury or damages arising in connection therewith. The views expressed are subject to change at any time.
These views should not be relied upon as investment advice, as portfolio positioning, as securities, recommendations or as an indication of trading intent on behalf of the advisor. No forecasts can be guaranteed.